
A Year of External Payments on iOS: What It Actually Did to App Economics
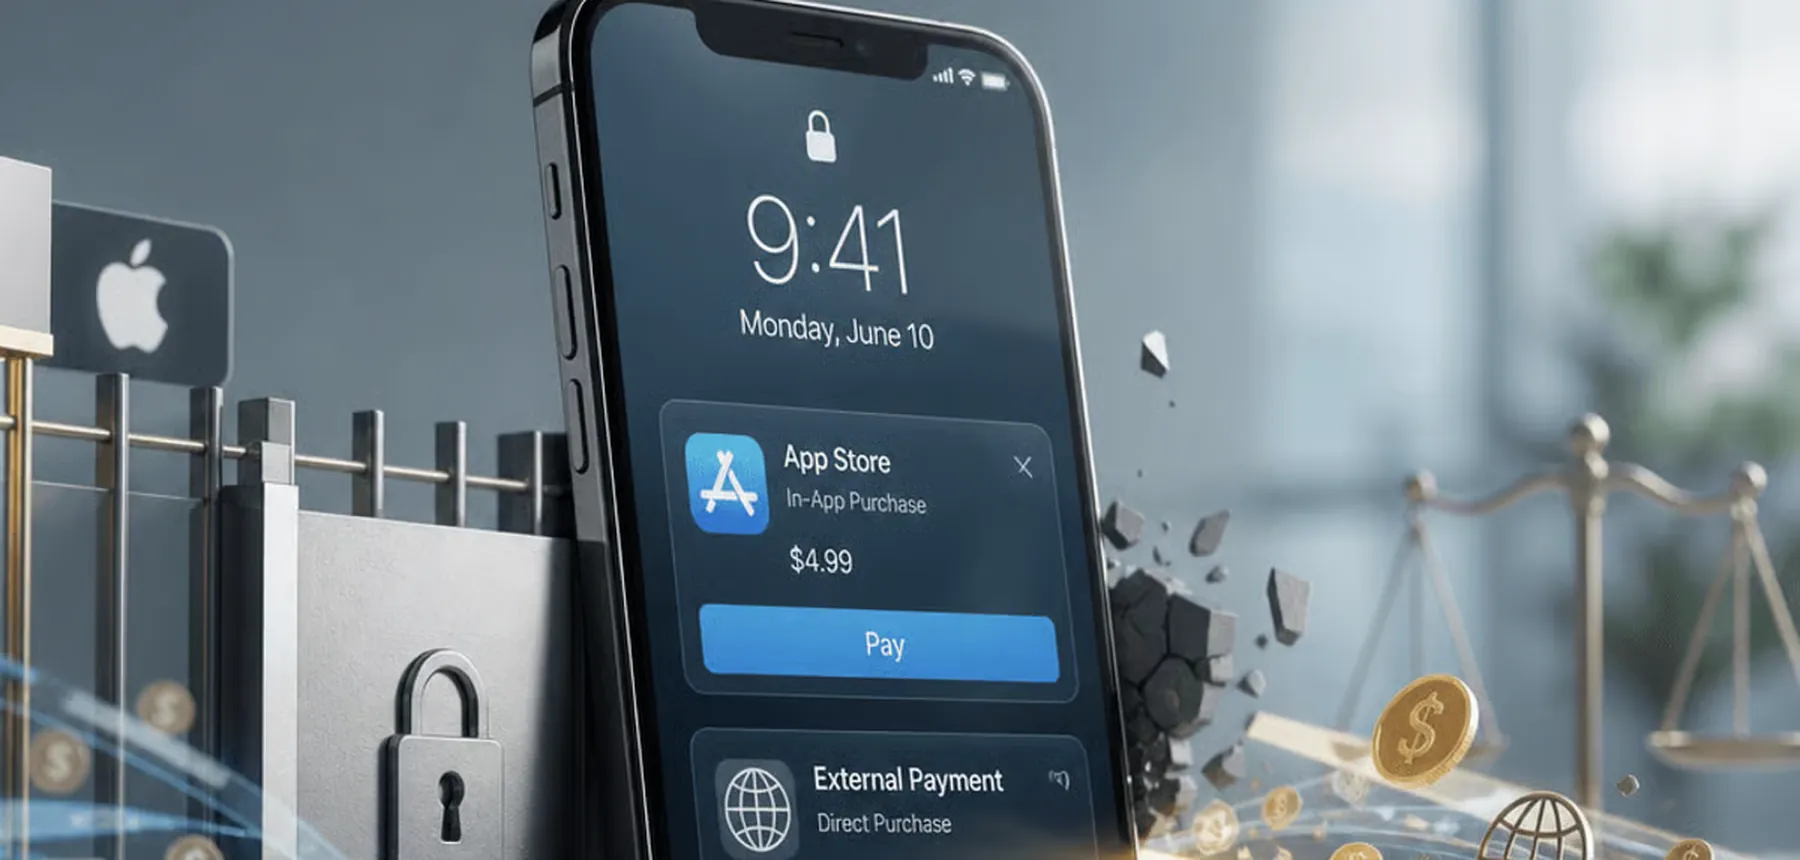
When the Epic ruling forced Apple to stop taxing and restricting external payment links in the US, it was read as an unambiguous developer win. A year of shipping against it gives a more useful picture: the margin is real, and it is not free.
What changed
Apps can link users to their own checkout without the platform commission on those transactions, without scare screens, and without restrictions on how the link is styled or placed. For a subscription business at scale, that commission is not a rounding error — it is often the difference between a viable acquisition cost and an unviable one.
What did not change
- Conversion friction is real. In-app purchase converts better because it is one tap against a stored credential. External checkout converts worse. Teams that skipped modelling that delta found the commission saving partly eaten by it.
- You now own payments. Chargebacks, tax handling, dunning, refunds, and PCI scope become your problem rather than the platform’s.
- Support load shifts. Subscription management questions come to you instead of to Apple.
- Jurisdiction matters. The ruling is US-specific. A global app needs both paths regardless.
The pattern that worked
Offer both. Keep in-app purchase for the impulse tier where conversion matters most, and route higher-value annual plans through your own checkout where the margin justifies the friction. Instrument both paths and let the data pick the default.
For FlutterFlow and Bubble teams already running Stripe on web and Android, the implementation cost is low — which is exactly why it is worth doing properly rather than switching wholesale and discovering the conversion hit at the next renewal cycle.